Roof Replacement Estimate vs. Final Cost: Why Supplements Close the Gap
Kelvin Spratt
Founder, Supplement Snap · March 10, 2026
What Changes the Final Cost
Hidden damage
Decking, flashing and extra layers are found at tear-off and are not in the first estimate
Key Takeaways
Why the first roof replacement estimate is lower than the final cost, what adjuster inspections miss, and how supplements bridge the gap.
Preparing a supplement? Use the free checklist so nothing is missing when you submit.
Why the initial estimate is always lower than the final cost
If you've been in the roofing business for any length of time, you already know this: the insurance adjuster's initial estimate almost never covers the full cost of replacing the roof. In an illustrative case, the estimate comes in at $9,500, but by the time your crew finishes the job, the actual cost is higher once hidden damage is found.
This gap between the initial estimate and the final cost isn't a mistake, and it isn't the adjuster being dishonest. It's a structural reality of how insurance roof inspections work. The adjuster inspects the roof from the surface. They walk it, note visible damage, and write an estimate based on what they can see. They don't tear off the shingles. They don't inspect the decking underneath. They don't check whether the flashing behind the chimney has corroded or whether the ice and water shield in the valleys has deteriorated.
The initial estimate covers the visible scope. The actual job includes everything hidden underneath. That's where the gap comes from, and it's why supplements exist: to close it.
What gets missed in adjuster inspections
Insurance adjusters are not trying to shortchange you. They're writing an estimate based on a surface-level inspection, and there's a long list of items that cannot be assessed without removing the existing roofing materials.
The most commonly missed items include:
Rotted decking: Plywood or OSB that has deteriorated from years of moisture penetration. The shingles on top may look fine, but the wood underneath is soft, spongy, or crumbling. Damaged decking is a common hidden cost, and the amount depends on how many sheets are affected and on local material and labor prices.
Failed step and counter flashing: Metal flashing at chimneys, walls, and dormers corrodes over time behind the shingles, invisible from the surface. Replacing flashing at a single chimney can add a few hundred dollars (illustrative; costs vary by region and material).
Missing or deteriorated ice and water shield: Many older roofs were installed before current building codes required ice and water shield in valleys, at eaves, and around penetrations. The added cost depends on coverage area and local prices.
Cracked pipe boots: Rubber gaskets around plumbing vents crack and split with age. Each pipe boot is a small cost, but they add up across a roof.
Additional layers of roofing: The original estimate may have been written for a single-layer tear-off. Additional layer removal adds cost per square, so it scales with roof size.
Missing drip edge: Older homes often lack drip edge entirely. Full perimeter replacement adds material and labor.
An illustrative example: estimate vs. actual cost
Here is an illustrative example with made-up round numbers. It is not a quote, not a customer result and not a typical outcome; prices vary by region, material and carrier. Consider a 25-square residential roof replacement on a home built in the early 2000s with storm damage.
The adjuster's initial estimate:
Tear-off (1 layer): $1,125
New architectural shingles: $4,500
Felt underlayment: $625
Ridge cap: $375
Pipe boot replacement (1 visible): $85
Haul debris: $562
O&P (20%): $1,454
Total initial estimate: $8,726
What the crew finds during tear-off:
3 sheets of rotted decking along the eave: $209
Corroded step flashing at the chimney (24 LF): $210
Missing ice and water shield in both valleys (180 SF): $333
2 additional cracked pipe boots: $170
Missing drip edge along the rakes (45 LF): $191
O&P on additional items (20%): $223
Total hidden damage: $1,336
The actual cost is now $10,062, a gap of $1,336. On more complex roofs with multiple penetrations, steep pitches, or older construction, the gap can be larger.
Multiply that across every insurance job you do. If hidden damage regularly goes undocumented across many insurance roofs, that is work you do without being paid for it, unless you submit supplements.
How supplements bridge the gap
A supplement is the formal mechanism for closing the gap between the initial estimate and the actual cost. It's a documented request to the insurance carrier saying: your adjuster estimated the visible damage accurately, but our crew found additional concealed damage during tear-off that needs to be covered.
A well-documented supplement includes:
Photographs of each concealed damage finding, taken during tear-off before new materials cover it up
A professional narrative explaining what was found, where it was located, why it was concealed, and why the repair is necessary
Xactimate line items with the correct codes, quantities, and current pricing
Building code references where applicable
When submitted with good documentation, supplements are easier to review, though the carrier makes the decision. Adjusters expect them because they know their surface inspection doesn't catch everything. The key word is 'properly.' A supplement with clear photos, a detailed narrative, and accurate Xactimate formatting gets approved. A supplement with a blurry photo and 'found some bad decking' gets denied.
The difference between contractors who consistently recover supplement revenue and those who don't comes down to documentation quality and submission speed.
Illustrative scenarios: estimate vs. final with supplements
Three fictional scenarios for illustration only. They are not customer results, and your numbers will differ:
Scenario 1: Simple ranch home, 20 squares
Initial estimate: $7,200
Hidden damage: 2 sheets rotted decking, 2 cracked pipe boots, missing drip edge on front eave
Supplement value: $680 + O&P = $816
Final cost with supplement: $8,016
Revenue recovered: 11% above initial estimate
Scenario 2: Two-story colonial, 30 squares, chimney and dormers
Initial estimate: $12,800
Hidden damage: 4 sheets rotted decking, corroded step flashing at chimney and 2 dormers, missing ice and water shield in valleys, 3 cracked pipe boots
Supplement value: $2,180 + O&P = $2,616
Final cost with supplement: $15,416
Revenue recovered: 20% above initial estimate
Scenario 3: Complex multi-level, 35 squares, multiple layers
Initial estimate: $14,500
Hidden damage: 6 sheets rotted decking, second layer of shingles, deteriorated ice and water shield, corroded flashing at 2 walls, 4 cracked pipe boots, missing drip edge full perimeter
Supplement value: $4,340 + O&P = $5,208
Final cost with supplement: $19,708
Revenue recovered: 36% above initial estimate
In every scenario, the supplement represents real work the contractor has to do regardless. The only question is whether they get paid for it.
How to systematically capture the difference on every job
Recovering supplement revenue can't happen only when someone in the office remembers. It needs to be a systematic part of your production workflow.
Here's what a systematic supplement process looks like:
Train every crew to recognize and document hidden damage during tear-off: rotted decking, corroded flashing, deteriorated pipe boots
Establish a documentation protocol: when damage is found, stop and photograph it before covering it with new materials. Wide-angle context shot and close-up detail shot.
Use a tool that makes documentation fast and easy. If it takes 20 minutes per finding, your crew won't do it. If it takes 30 seconds to snap a photo and tag the damage type, they'll do it every time.
Generate the supplement report the same day. Don't let findings sit in someone's camera roll for a week.
Track supplement status for every job: submitted, pending, approved, denied. Follow up weekly.
Contractors who build documentation into their standard workflow are better placed to request payment for hidden damage. Those who treat it as an afterthought are more likely to leave work unpaid.
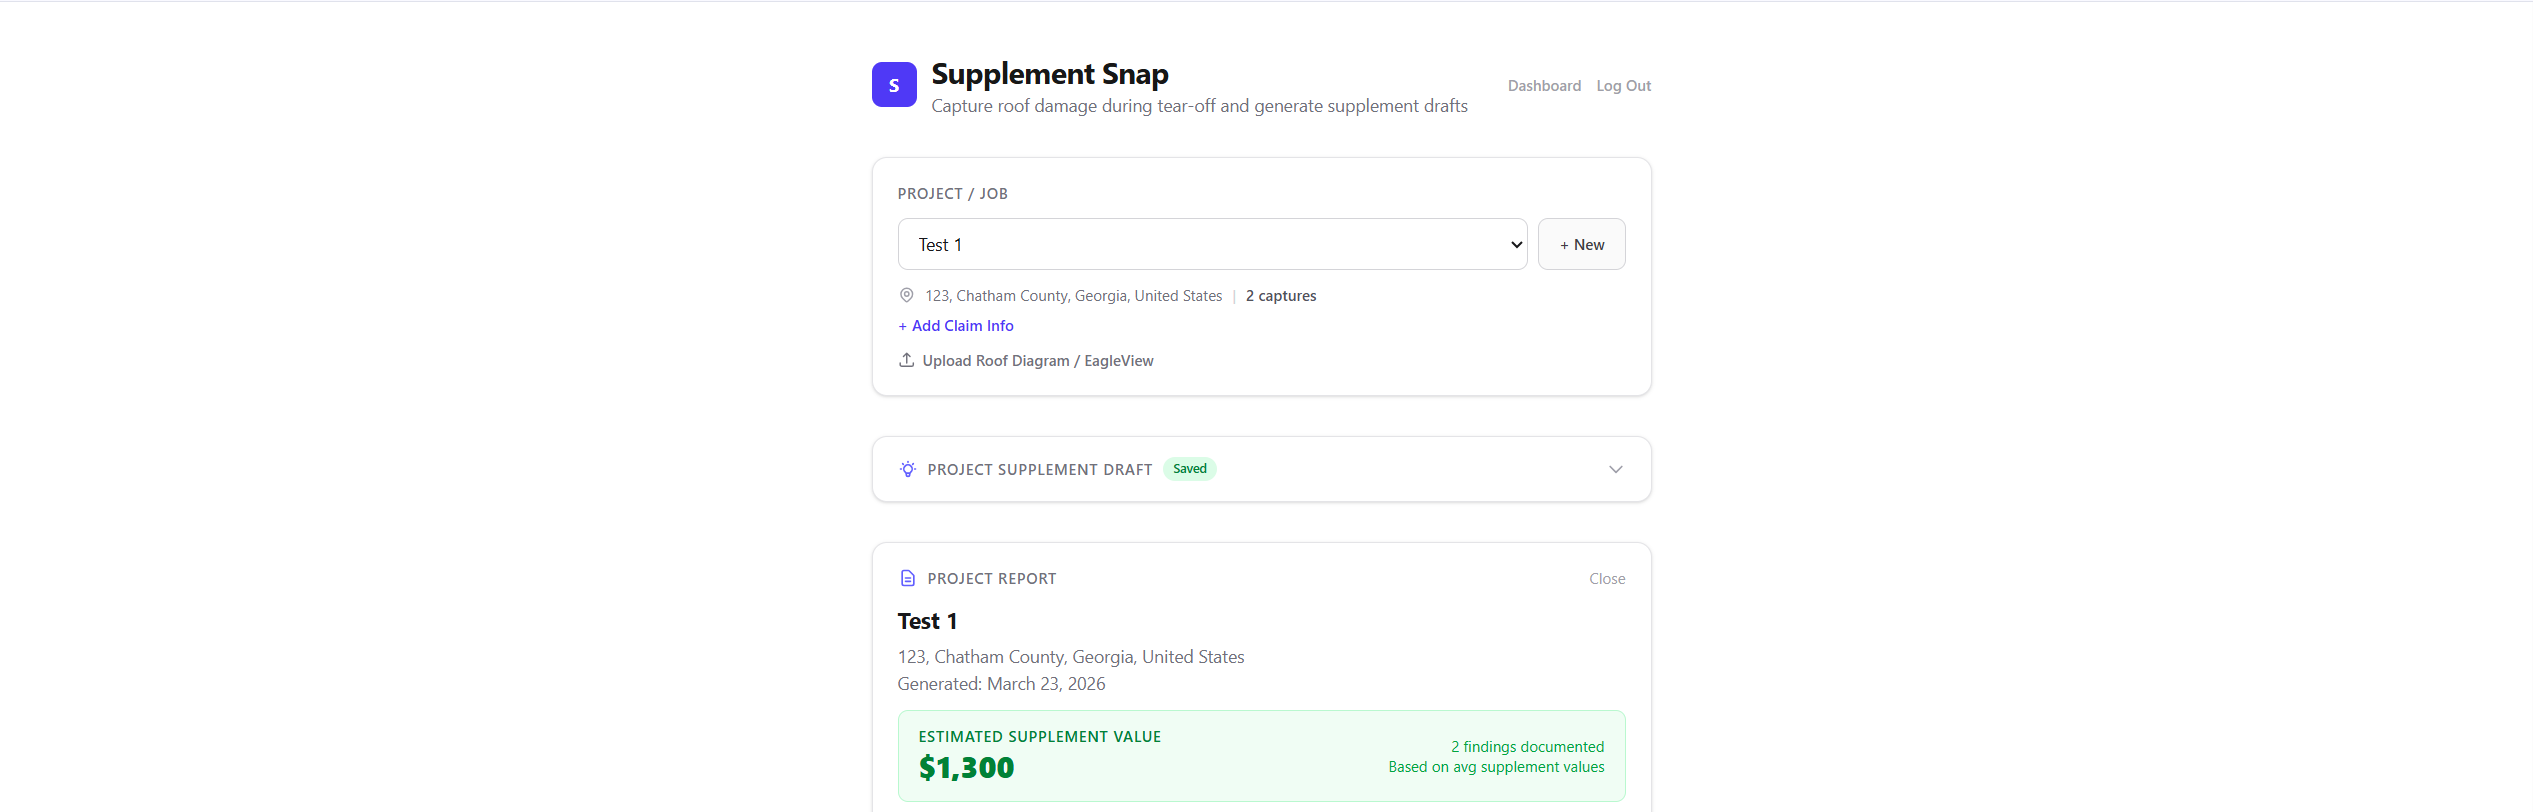
Close the gap with Supplement Snap
Supplement Snap was built to make this systematic approach effortless. During tear-off, the crew opens the app and captures each finding: a photo tagged with the damage type and roof area, plus an optional voice note. Voice notes work in Spanish and other supported languages. Spanish-speaking crews describe findings in Spanish and the system auto-translates to English.
From that field data, Supplement Snap generates everything you need:
A professional supplement narrative for each finding, written in the language adjusters expect
Suggested Xactimate-style line items with codes and quantities for you to review and price
An Xactimate-style CSV export on Team and Pro plans, a starting list you review and price yourself
A branded PDF report with photos, narratives, findings summary, and line items, ready to email
The entire process from capturing damage on the roof to emailing a complete supplement report takes minutes, not days. Your crew does what they're already doing (finding damage during tear-off) and Supplement Snap turns those findings into revenue.
The gap between the initial estimate and the final cost will always exist. The question is whether you have a system to capture it. With Supplement Snap, every hidden finding becomes a documented, submitted, trackable supplement, and you get paid for the work you're actually doing.
Curious about actual supplement values? See how much roofing supplements pay.
References & Resources
Free tools and resources
Ready to streamline your supplement process?
Supplement Snap helps your crew capture hidden damage during tear-off and generate adjuster-ready reports in minutes.
Written by
Kelvin Spratt
Founder, Supplement Snap
Kelvin builds software for roofing contractors who are tired of leaving supplement money on the table. His background in software development and insurance restoration workflows drives everything Supplement Snap does.
More Articles
Roofing Permit Fees on an Insurance Claim: How to Request Them
Read more →
Insurance Lowball Roof Estimate: What Roofers and Homeowners Can Do
Read more →
Roof Tear-Off Cost in 2026: What Contractors and Homeowners Should Know
Read more →
Code Upgrades in Roofing Claims: Ordinance and Law Coverage Explained
Read more →